A nation downgraded, a Bank in the red: Is SVG’s debt risk coming home to roost?
 17 October 2026
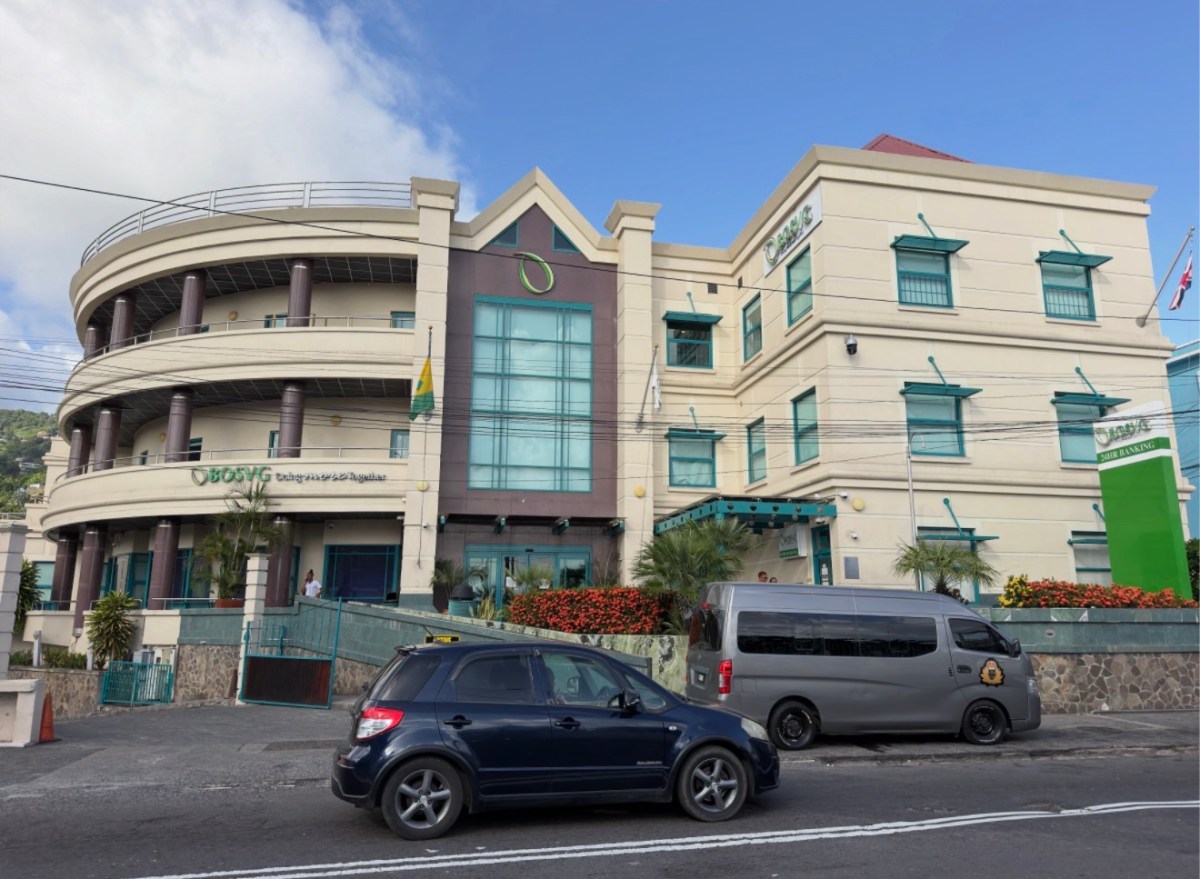

BOSVG records EC$15M loss during first half of 2026 amid SVG’s credit downgrade
By Admin. Updated 9:29 a.m., Saturday, October 17, 2026, Atlantic Standard Time (GMT-4).
The Bank of St. Vincent and the Grenadines (BOSVG) recorded an unaudited net loss of EC$15.03 million for the first six months of 2026, marking a sharp reversal from the EC$21.81 million profit reported during the same period last year. However, a closer examination of the bank’s interim financial statements suggests the headline figure tells only part of the story.
Rather than pointing to a collapse in the bank’s day-to-day operations, the loss was overwhelmingly driven by a dramatic increase in allowances for credit losses. That expense surged to EC$42.28 million, compared with just EC$2.13 million in the first half of 2025, an increase of more than EC$40 million. According to the financial analysis, that single item explains approximately 98 per cent of the year-on-year deterioration in the bank’s pre-tax results.
The figures indicate that BOSVG’s underlying banking business continued to generate income.


Operating income edged up from EC$60.31 million to EC$61.41 million, while earnings before impairment remained positive at EC$27.25 million. In other words, the bank was still earning money from its core operations before the sizeable credit-loss charge was recognised.
The report also shows that net interest income increased by 5.8 per cent to EC$41.95 million, although fee and other non-interest income declined by 15.5 per cent. Operating expenses rose six per cent over the period, placing additional pressure on profitability.
Management has attributed the deterioration in earnings primarily to additional credit-related provisions. It also disclosed that a one-time EC$1.4 million loss arising from a Trinidad and Tobago dollar transaction affected non-interest income, but the analysis concludes that this currency-related loss was not the principal reason for the bank’s overall half-year deficit.
Meanwhile, the bank’s balance sheet continued to expand during the first half of the year.


Total assets grew to just over EC$2.3 billion, customer deposits increased to approximately EC$2 billion, and the value of customer loans rose by 7.7 per cent. Despite that growth, shareholders’ equity declined by nearly 17 per cent, falling from EC$214.93 million at the end of 2025 to EC$178.93 million by June 30.
The analysis attributes that decline in equity to three factors: the EC$15.03 million loss, almost EC$20 million in dividend payments, and just over EC$1 million in negative fair-value movements on investments. It notes that the dividend payment represented the single largest component of the reduction in equity, while adding that the available interim information does not establish whether those dividends were approved before the deterioration in earnings became apparent.
Although the financial statements identify the unprecedented rise in credit-loss provisions as the central issue, they stop short of explaining exactly what caused the increase.
The published figures do not disclose how much of the EC$42.28 million provision relates to customer loans, investment securities or other financial assets. Nor do they identify which borrowers, industries or counterparties accounted for the increase, or whether the provisions were driven by new loan defaults, changes in collateral values, revised economic assumptions or adjustments to the bank’s credit-risk models.

The timing of the provision has also drawn attention because it coincided with a downgrade of St. Vincent and the Grenadines’ sovereign credit rating by Moody’s Ratings. On June 30, 2026, the agency lowered the country’s long-term sovereign rating from B3 to Caa1 and revised its outlook from stable to negative, citing rising public debt, increasing financing needs, tighter government liquidity and greater reliance on a small number of domestic financial institutions. Importantly, the downgrade does not mean the Government has defaulted or that a debt crisis is inevitable. Rather, it signals that the country’s credit risk has increased.
Why does that matter to ordinary Vincentians? Government bonds are widely held by commercial banks because they provide interest income and are generally regarded as relatively secure investments. However, when a country’s creditworthiness weakens, those bonds may carry greater perceived risk. Under international accounting rules (IFRS 9), banks may be required to increase expected credit-loss provisions on financial assets even if no actual default has occurred. The evidence currently available does not establish that Moody’s downgrade caused BOSVG’s EC$42.28 million credit-loss charge.
Nevertheless, the combination of the downgrade and the bank’s sizeable impairment provision raises legitimate questions about how much, if any, of the provision relates to government-related exposures. Only a detailed breakdown of the bank’s impairment calculations can answer that definitively.
The analysis further highlights several unresolved issues requiring clarification, including the distribution of exposures across IFRS 9 credit-risk stages, the strength of the bank’s capital position following the impairment charge, its dividend policy for the remainder of the year, and the reasons cash and cash equivalents declined by roughly EC$98 million during the first six months of 2026.
BOSVG has reported non-performing exposures of EC$37.5 million, representing 3.4 per cent of its portfolio, together with a capital adequacy ratio of 19.5 per cent and a liquidity ratio of 20.1 per cent. However, the analysis notes that the abbreviated interim statements do not contain sufficient detail to independently verify those regulatory measures.
The report concludes that the bank’s half-year performance should be viewed primarily as an impairment-led loss rather than a breakdown in its operating business. Even so, it cautions that the underlying cause of the EC$42.28 million credit-loss charge remains unclear.
Whether the provision reflects a prudent one-off clean-up of the loan portfolio, problems involving one or more major borrowers, or signs of broader deterioration in credit quality cannot be determined from the interim statements alone.
According to the analysis, only the release of the underlying IFRS 9 credit-risk schedules and detailed supporting notes will provide a definitive explanation.
END
The following images show bank’s publicly published half-year report for 2026.


Related News
US$100 Million Eco-Resort Planned for Mayreau as Invest SVG, Nativo Group Sign Agreement
U.S. Consular Officer to Offer Passport Services in SVG by Appointment
One dead after alleged foiled robbery at cannabis farm in Dickson